 Web & Software Development
How Celion Builds a Website: From First Message to Launch
Celion builds websites not as decoration, but for a business purpose: we map the customer journey, add security from the...
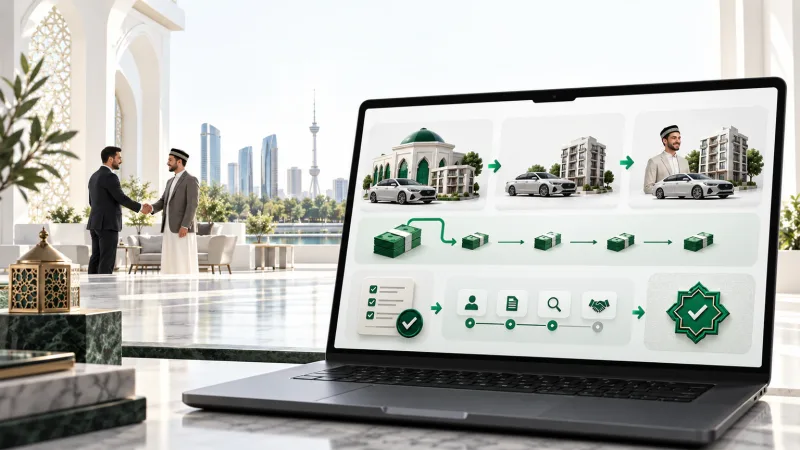
A strong Islamic banking website checklist starts with the essentials: explain how the product works, what it costs, who it suits, and what happens after the application is submitted. If customers cannot find this information, they will call the contact center or abandon the form.
Treating an Islamic finance page as an advertising page is a mistake. It should help customers make a decision. When Murabaha or Ijarah, required documents, and responsibility for Shariah compliance are explained in one clear flow, repetitive questions decrease. The bank also receives fewer applications from customers who do not meet the requirements.
Before customers click the "Apply" button, they should know who the product is for and what the financing can be used for. The currency, term, calculation of the bank’s profit, and collateral requirements should also appear here. “Contact us for details” is not a substitute for clear terms.
This is also a legal requirement. Uzbekistan’s banking legislation requires banks to publish service terms, fees, tariffs, and pricing information openly on their official websites. Following monitoring by the Central Bank, each bank whose website information was found to be incomplete received a fine of 102 million soums.
Shariah compliance cannot be reduced to a generic promise at the bottom of the page. The product page should include a brief explanation of the transaction and the relevant opinion. Create a separate page for the Islamic Finance Council’s membership, authority, approval process, and audit procedures. Putting this information only in a PDF makes it harder for users to verify. The council’s responsibilities are clearly defined by law.
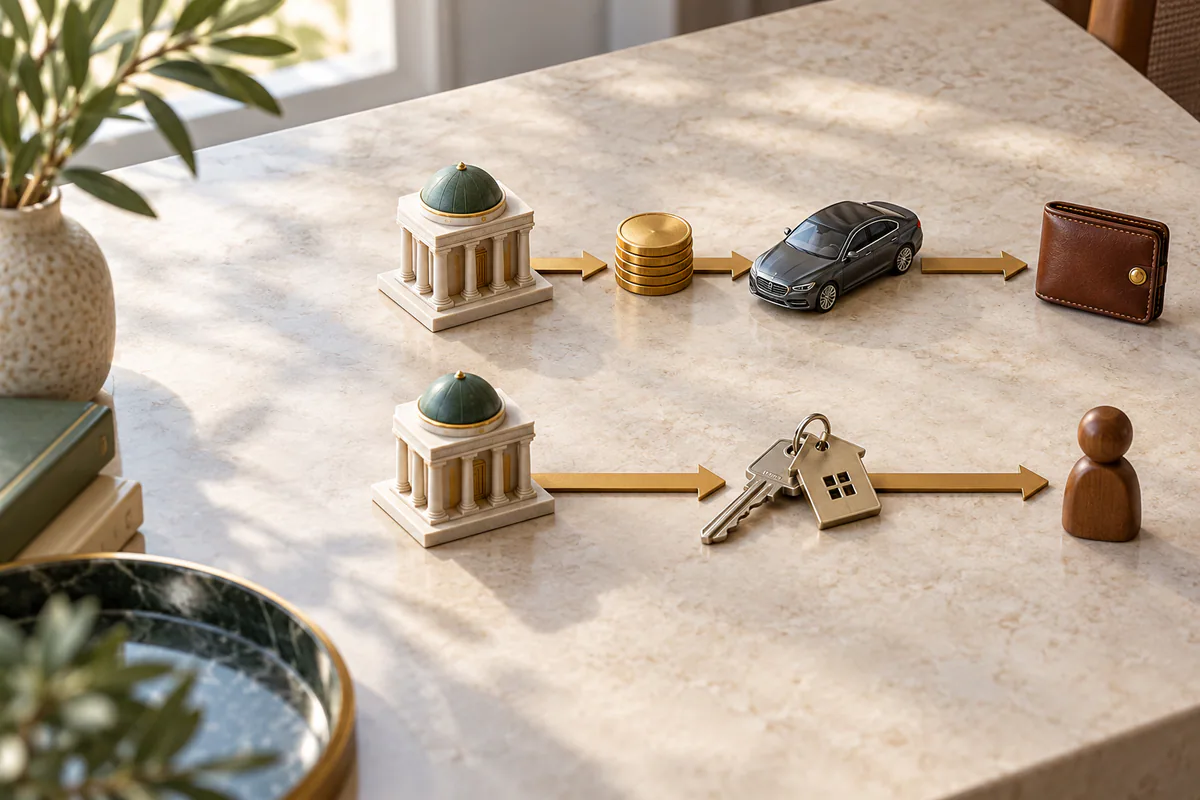
Defining Murabaha as “a sale with a markup” is accurate, but it does not fully explain the transaction to the customer. The website should show the process step by step: the bank buys the asset selected by the customer, sells it to the customer at an agreed markup, and then sets a payment schedule. Show the asset price, the bank’s markup, and the total payment separately.
The Ijarah page should state clearly who owns the asset. The customer selects the asset, the bank purchases it, and the customer makes lease payments for the right to use it. Once the terms have been fulfilled, ownership is transferred under a separate procedure. Ipak Yuli Bank’s explanation also describes the process through the purchase, lease, and subsequent transfer of ownership. This kind of diagram communicates the difference between Murabaha and Ijarah faster than a long legal text.
The Uzbek and Russian pages should have the same structure, meaning, and update date. If an English version is needed for the audience, the same requirement applies to it. Providing complete terms in one language while leaving only a phone number in another is wrong. All language versions should be managed as equal representations of the same product information.
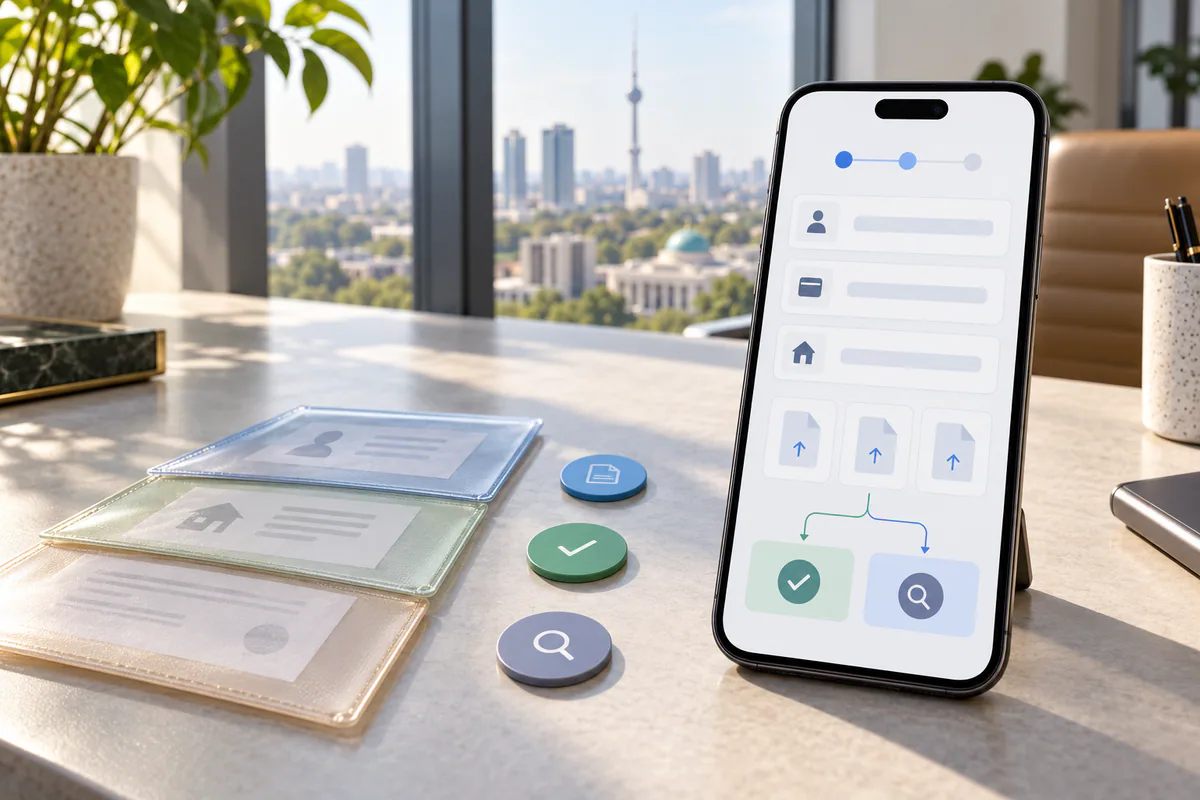
Simplifying an Islamic banking online application does not mean removing every question. Start by collecting only the brief information needed to determine whether the customer is eligible for the product. Leave financial documents and identity verification for later stages. If the company name, taxpayer identification number, product type, and contact details are enough to get started, asking for collateral documents on the first screen creates unnecessary friction.
Customers will close the application if they do not understand a question, do not have the required document at hand, or cannot save their progress and continue later. Slow mobile internet can also be a factor. Accion’s research on Central Asia shows that slow connections and basic devices limit access to digital services. The form should therefore load quickly on mobile, save entered information, and explain in plain language why each document is required.
Answers to recurring questions should appear on the product page or next to the relevant field. For complex cases, let customers switch to an operator through Telegram, request a call, or receive advice using their application number. Preselecting consent checkboxes or filling in parameters on the customer’s behalf is not a convenience. Consumer protection rules restrict these practices.
Measuring only the overall conversion rate is not enough. The bank should record when each stage is opened, where errors occur, whether documents are uploaded, and when customers save and exit. Applications resumed later should also be measured separately. The completion rate is calculated by dividing the number of submitted applications by the number of started applications. Funnel analysis by stage shows the exact field where customers drop out.
Do not begin a bank website UX checklist with the design mockup. Begin with questions from the contact center. Ask operators which questions customers repeatedly raise about Islamic financing, then place the answers in the relevant parts of the product page. The product owner should verify their accuracy. A lawyer and a representative of the Islamic Finance Council should review the text within the same editorial process.
If the responsible bank department cannot update application statuses, is not ready to accept documents digitally, or has no defined response time, do not rush to launch a fully online application. Use a short screening form and tell customers when and how they will be contacted next. Every digital step promised on the website must have a responsible owner and a clearly defined status in the bank’s internal process.
Celion uses UX audits to review product pages, multilingual content, and online application flows on banking websites. During website development, Celion connects these elements into a single system supported by funnel analytics.
Callback
Leave your details and we will contact you shortly.
Become a Partner
Leave your contact details and we will get back to you shortly.
Order Service
Leave your phone number and we will contact you shortly.